The finance committee of a church in Lakeland meets to review its insurance renewal. The congregation has grown, the fellowship hall now hosts a weekday food pantry, the youth group took two trips in a rented van last summer, and the board approved a part-time administrator and a worship leader. The renewal in front of them looks almost exactly like the policy the church bought eight years ago. Nobody on the committee is sure whether that is a problem, and nobody wants to be the one to find out after a loss.
That situation is more common than most church leaders realize. A church’s insurance program tends to be set up once and then renewed on autopilot, while the ministry itself keeps changing. The coverage a church needs depends on what it owns, what it does, who it serves and who works or volunteers there. Understanding what each piece of the program does, and what triggers the need for it, is the starting point for knowing whether the policy still fits.
Property Coverage for the Building and Its Contents
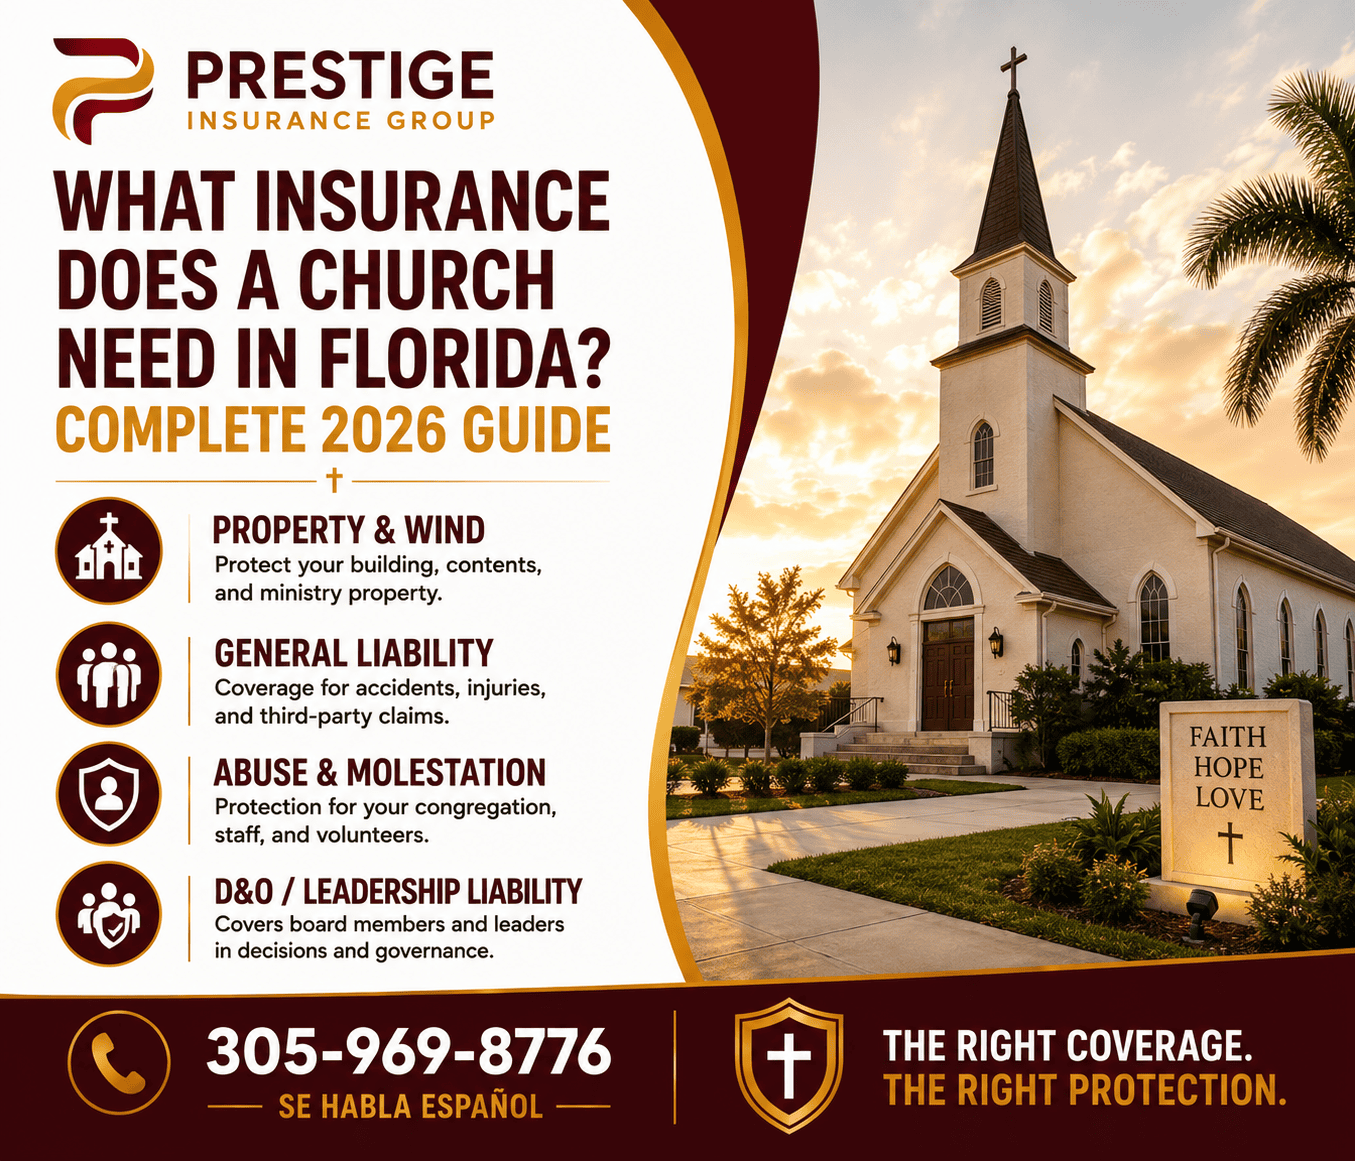
For most churches, the building is the largest asset the congregation owns, and property coverage is the foundation of the program. It pays to repair or rebuild the sanctuary, fellowship hall, classrooms and offices after a covered loss such as fire, wind, lightning, water damage from a burst pipe or vandalism. It also covers contents, which in a church often include pews, pianos and organs, sound and video systems, kitchen equipment and furnishings that would be expensive to replace all at once.
The most important decision on the property side is the building limit. A church insured for less than what it would actually cost to rebuild can find itself short after a major loss, and older sanctuaries with stained glass, vaulted ceilings or custom woodwork often cost far more to rebuild than their age suggests. In Florida, windstorm deductibles and roof condition shape both the price and the terms, which we cover in more detail in our article on church roof coverage and insuring your building to value.
General Liability for Everyday Ministry
General liability protects the church when someone is injured on its property or because of its activities, or when the church damages someone else’s property. A visitor who slips on a wet floor in the lobby, a guest who trips over a cord during a concert or a child hurt on the playground are typical general liability claims. The coverage also pays for the church’s legal defense, which can cost as much as the claim itself.
A church’s liability exposure grows with its activities. Festivals, sports leagues, food pantries, concerts, weddings for non-members and outside groups using the building all add people and situations that the policy needs to account for. If the church rents its space to other organizations, it should also understand the steps outlined in our guide to renting your church facility to outside groups.
Abuse and Molestation Coverage
Any church that works with children, youth or vulnerable adults needs to look closely at abuse and molestation coverage. Many general liability policies exclude these claims entirely or provide coverage only through a separate endorsement with its own limit. The details matter a great deal: how much coverage is available, whether the policy is written on an occurrence or claims-made basis, and what screening and training the carrier requires as a condition of coverage.
This is also an area where underwriters ask the most questions, and where a church’s own safeguards, such as background checks, two-adult rules and documented training, directly affect whether coverage is available. Our article on abuse and molestation coverage for Florida churches explains what to review.
Directors and Officers Liability
Church boards, elders, deacons and trustees make decisions about money, property, personnel and membership. When someone disagrees strongly enough with one of those decisions, the result can be a lawsuit alleging mismanagement, wrongful termination, breach of duty or discrimination. General liability does not respond to those claims because they do not involve bodily injury or property damage. Directors and officers liability fills that gap, and many policies also include employment practices coverage, which is increasingly important for churches with paid staff.
Auto Coverage, Including Vehicles the Church Does Not Own
A church that owns a van or bus needs a commercial auto policy on that vehicle. But even a church that owns no vehicles has an auto exposure, because staff and volunteers drive their own cars on church business, and the church can be named in a lawsuit when one of them causes an accident. Hired and non-owned auto coverage protects the church in those situations. It is inexpensive relative to the protection it provides and belongs on almost every church program, as we explain in our article on church vans and volunteer drivers.
Workers’ Compensation and Volunteers
Florida requires most non-construction employers with four or more employees, full-time or part-time, to carry workers’ compensation, and religious organizations with paid staff are generally included. Pastors, administrators, custodians, musicians and childcare workers can all count toward that threshold. Even when a smaller church is not required to carry it, a workers’ compensation policy is often the most practical way to protect both the employee and the church after a workplace injury.
Volunteers are a separate question. They are generally not treated as employees under Florida’s workers’ compensation law, which means an injured volunteer may look to the church’s liability coverage or to a volunteer accident policy instead. Churches that rely heavily on volunteers for construction projects, maintenance or events should review how those injuries would be handled.
Umbrella, Crime and Equipment Coverage
An umbrella policy sits above the general liability, auto and sometimes abuse coverage, adding limits for a serious claim that exceeds the underlying policies. For churches with vans, large events or schools, it is often the most cost-effective way to raise overall protection.
Crime coverage protects against theft of money by employees or volunteers, forgery and certain fraud. Churches handle cash offerings, online giving and payments to vendors, and internal theft is one of the more common and painful losses a congregation can face. Equipment breakdown coverage addresses the sudden failure of air conditioning, electrical systems and boilers, which in Florida can shut down a sanctuary at the worst possible time. Churches that carry audio, video and musical equipment off site for missions or events may also need inland marine coverage for that property.
When the Program Needs a Second Look
A church’s insurance should be reviewed whenever the ministry changes in a meaningful way. Opening a preschool or daycare, starting a school, adding paid staff, buying a vehicle, renovating or expanding the building, hosting regular outside events or offering counseling services are all moments when the coverage may no longer match the risk. Each of those changes is covered in more depth in the articles linked throughout this guide and on our church insurance page.
Worth Confirming With Your Agent
-
Whether the building limit reflects the current cost to rebuild, including special features
-
Whether abuse and molestation coverage is included, at what limit and on what basis
-
Whether the policy includes directors and officers and employment practices coverage
-
Whether hired and non-owned auto coverage is in place, along with coverage for any owned vehicles
-
Whether the church’s paid staff count triggers Florida’s workers’ compensation requirement
-
Whether crime coverage protects against theft of offerings and online giving
-
Whether an umbrella policy sits above the liability and auto coverage
This article is general information and is not legal advice.
Talk to Prestige Insurance Group
Prestige Insurance Group works with churches across Florida, from small congregations meeting in storefronts to campuses with schools, preschools and vehicles. We review the whole program, explain what each coverage does and look for gaps before a claim finds them.
Call the office nearest you. Se habla español.
Orlando: 407-993-2331
Miami: 305-969-8776
Stuart: 772-247-3788
Prestige Insurance Group, License L057894