


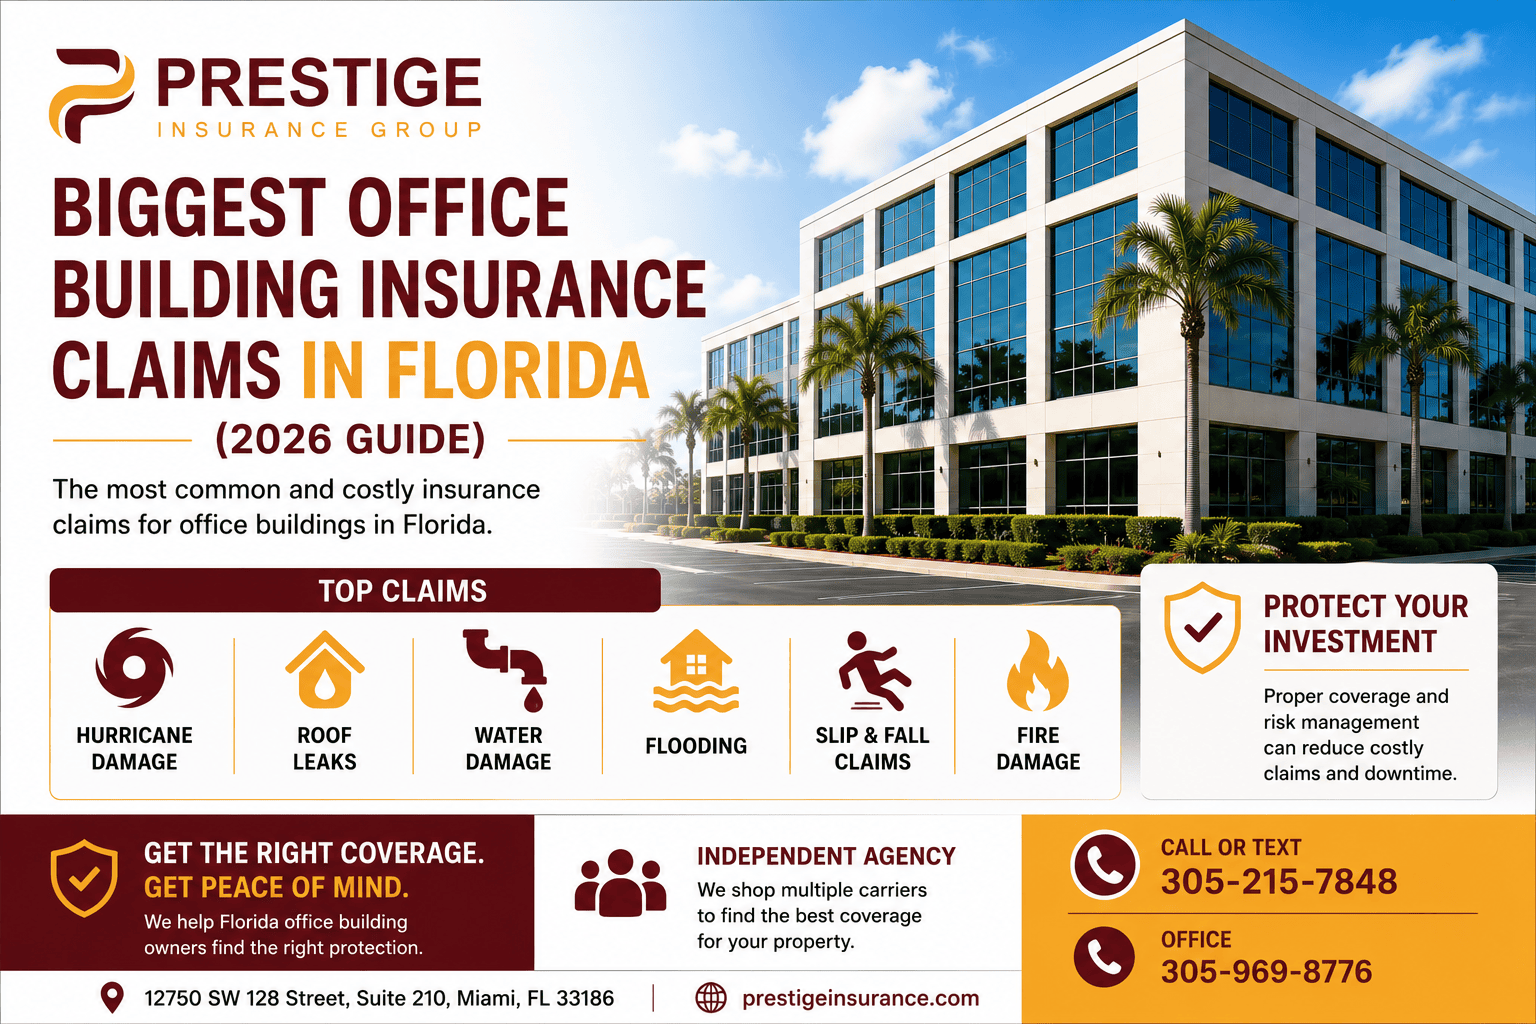
The owner of a three-story office building in Doral thought of his insurance mainly in terms of hurricanes. Over ten years of ownership, his claims told a different story: two water losses from failed supply lines in tenant suites, a roof leak that damaged a medical tenant’s equipment, and a slip and fall lawsuit from a visitor in the lobby. The one hurricane claim was the largest, but the others added up to more.
That pattern is typical. Office buildings in Florida produce a handful of claim types over and over, and knowing them is the best guide to how a policy should be built.
Hurricane and Windstorm Damage
Wind is the largest single exposure for most Florida office buildings. Roof coverings, rooftop equipment, windows, storefront glass and signs take the damage, and water entering through those openings ruins ceilings, flooring and tenant improvements. Windstorm deductibles are usually a percentage of the insured value, so even a moderate storm can leave the owner with a substantial share of the loss. Our guide to hurricane insurance for office buildings explains how wind coverage and deductibles work.
Water Damage From Inside the Building
Plumbing failures, water heaters, sprinkler leaks, clogged air conditioning drains and backed-up restrooms are the most frequent office building claims. In a multi-tenant building, one failure can damage several suites, the common areas and tenants’ property, which raises questions about whose policy pays for what. See our article on water damage claims in office buildings.
Roof Leaks
Roof claims often start as small leaks that go unnoticed until ceiling tiles fall or mold appears. Carriers look closely at roof age and condition, and damage from wear and long-term leaks is excluded. Our article on roof insurance problems for office buildings covers the issues owners run into.
Slip, Trip and Fall Injuries
Lobbies, parking lots, sidewalks, stairs and elevators all produce liability claims. Wet floors near entrances, uneven pavement, poor lighting and elevator malfunctions are common causes, and Florida’s legal environment can make even modest injuries expensive to defend. General liability and a commercial umbrella policy are the protection. See our guide to office building liability insurance.
Lost Rental Income
After a major loss, the building may lose rent for months while repairs are made. Business income or rental income coverage pays that lost rent, and it is often the coverage owners are most grateful for after a hurricane. Limits should reflect how long repairs would realistically take in a busy post-storm market.
Flood
Flood is excluded from commercial property policies. Storm surge and heavy rain can flood ground-floor suites, lobbies, parking garages and building systems. See our article on flood insurance for office buildings.
Using Claims History to Build Better Coverage
The claims above point directly to the coverage decisions that matter: adequate building limits, a windstorm deductible the owner can absorb, rental income coverage sized for a long restoration, strong liability limits, water damage prevention, and a separate flood policy where it makes sense. For a complete overview, see our page on office building insurance in Florida.
Call the office nearest you. Se habla español.
Miami: 305-969-8776
Orlando: 407-993-2331
This article is general information and is not legal advice. Coverage depends on the terms of each policy.



